CELEBRATING MORE THAN YEARS
AWARDS & RECOGNITION


PRACTICE AREAS

Dispute Resolution

Insolvency & Restructuring

General Corporate & Corporate Advisory

Real Estate & Property Laws

Employment & Labour Law


Intellectual Property Rights

Mergers / Amalgamations / Business Transfer

Foreign Investments

Tax

Banking & Finance

Cyber Law, Privacy, Data Protection & Information Technology

Startups
View All Practice Areas
PEOPLE
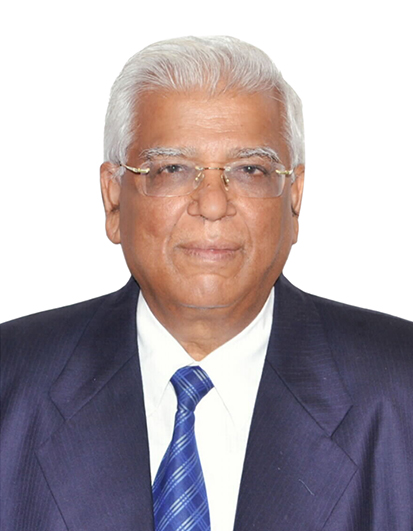
RA ShahManaging Partner
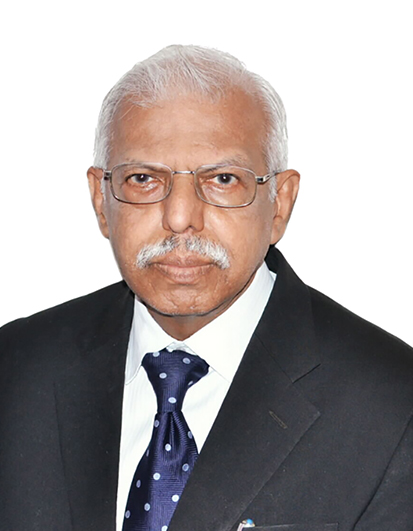
Niranjan parekhSenior Partner
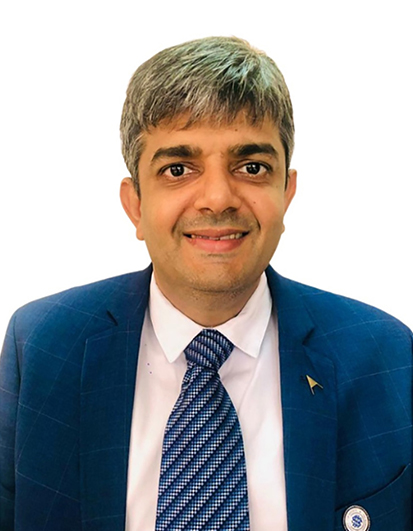
Bhushan ShahPartner
Purvi AsherPartner
Meeta kadhiAssociate Partner
Akash JainAssociate Partner
Sanjana SaddyOf-Counsel
Bhavin shahOf-Counsel
Neha LakshmanAssociate partner
News and Articles
Indian Subsidiary Setup
What Legal Issues Should Overseas Parent Companies Address When Setting Up an Indian Subsidiary?
An Indian subsidiary gives an overseas parent company a separate Indian legal entity through which it can conduct eligible business, hire employees, enter contracts and invest in local operations. However, Indian Subsidiary Setup involves more than incorporation. The parent must assess foreign direct investment rules, ownership restrictions, director and shareholder requirements, tax exposure, banking arrangements, intellectual property rights and ongoing compliance.
The right approach is to address these issues before incorporation, rather than treating them as administrative tasks after the company is registered. The analysis below focuses on the legal decisions an overseas parent should make, the key Indian regulatory frameworks and the risks to manage before and after launch.
1. Choose the Right Structure for the Indian Operation
An overseas parent can establish an Indian presence through different structures, including an Indian subsidiary, a branch office or a liaison office, subject to the relevant rules. The right option depends on the proposed activities, revenue model, operational needs and regulatory permissions.
A subsidiary is a separate legal entity incorporated under Indian company law. It can generally enter contracts, employ staff, hold assets and conduct business within the scope of its permitted activities. The parent’s liability is usually limited to its investment, subject to applicable law and the circumstances of the case.
A branch office is an extension of the foreign company rather than a separate Indian company. Its permitted activities are restricted by the applicable foreign exchange framework and approval conditions. A liaison office generally has a narrower role, such as representing the overseas parent or facilitating communication, and cannot be used as a substitute for an operating business where commercial activity is prohibited.
For many overseas businesses planning a long term commercial presence, a private limited subsidiary may be suitable. However, the structure should be selected only after checking the proposed activities and the relevant regulatory conditions.
2. Check Foreign Direct Investment Eligibility
Before committing funds, the parent should confirm whether foreign direct investment (FDI) is permitted in the proposed business sector and identify the applicable entry route.
Under the automatic route, eligible foreign investment can proceed without prior Government approval, subject to the applicable conditions. Under the Government route, prior approval is required for specified sectors or circumstances. Some sectors also have foreign investment caps, licensing requirements or operating conditions.
The analysis should focus on the subsidiary’s actual business activities, not merely its proposed name or broad corporate objects. A company planning to provide software services, for example, may face a different regulatory position from one operating in defence, insurance, broadcasting or another regulated sector.
The parent should also review restrictions linked to the investor’s ownership and control. Rules concerning entities or beneficial owners from countries sharing a land border with India may affect the proposed investment. A group structure involving several intermediate holding companies should therefore be examined carefully.
The RBI Master Direction on Foreign Investment in India is a key regulatory reference. The parent should check the current rules and applicable sectoral policy before finalising the investment.
3. Plan the Shareholding and Governance Structure
The parent should decide whether the Indian subsidiary will be wholly owned or jointly owned with an Indian or overseas partner. The ownership structure affects control, decision making, funding and exit arrangements.
A private company generally requires at least two members and two directors, with at least one director satisfying the statutory requirement concerning residence in India during the financial year. A wholly owned subsidiary can therefore require a suitable second member to hold shares on behalf of the parent, where appropriate. The arrangement should be properly documented and must reflect the genuine ownership and control position.
The company’s memorandum and articles of association should reflect its intended activities, share capital and governance arrangements. Where the parent wants to reserve important decisions for group approval, the articles and relevant internal documents should be drafted carefully.
The group should also decide who will appoint directors, approve budgets, authorise bank transactions and supervise compliance. These arrangements are particularly important where the subsidiary will handle significant contracts, employ staff or receive funding from the parent.
4. Prepare the Incorporation Documents Correctly
The incorporation process requires accurate corporate and identity documents from the overseas parent, proposed shareholders and directors.
Depending on the circumstances, the documents may include the parent’s certificate of incorporation, constitutional documents, board resolution authorising the Indian investment, details of authorised signatories, identity and address proofs, and declarations required for incorporation. Documents executed overseas may need notarisation, apostille or consular authentication, depending on the country and the applicable rules.
The proposed Indian company must also have an appropriate registered office address and comply with the prescribed name and incorporation requirements. The name should not conflict with existing company names or protected trademarks, and any use of the parent’s brand should be authorised.
Incorporation applications are generally filed electronically through the Ministry of Corporate Affairs system, using the prescribed forms and linked services. Errors in foreign corporate documents, inconsistent spellings or incomplete authorisations can lead to queries and delays.
The parent should coordinate the documents early with its legal team and the professionals handling incorporation. This is especially important where multiple overseas entities will subscribe to shares or where documents must be signed in different jurisdictions.
5. Structure the Initial Funding and FEMA Reporting
The overseas parent should determine how the subsidiary will be funded. Common options include equity investment, eligible preference shares, permitted debt arrangements and operating revenue generated after launch. Each route has different legal, tax and reporting consequences.
Equity funding from a non resident investor must comply with the applicable FEMA framework, including rules on entry routes, sectoral limits, pricing and reporting. The subsidiary should arrange the inward remittance through an appropriate banking channel and retain clear evidence of the source and receipt of funds.
Where shares are issued to the foreign parent, the Indian company must complete the relevant corporate approvals and foreign investment reporting. Depending on the transaction, this may include reporting the issue of equity instruments through the prescribed RBI process, such as Form FC GPR. The precise filing and deadline should be verified against the current rules.
Funding through debt requires separate consideration. An overseas parent loan is not automatically permitted simply because the lender owns the subsidiary. The parties must assess whether the borrowing complies with the external commercial borrowing framework or another permitted route, including applicable eligibility, maturity, cost and reporting conditions.
Careful planning at the outset helps prevent funding delays and reduces the risk of later regularisation work.
6. Understand Corporate Tax and Transfer Pricing
An Indian subsidiary is generally subject to Indian tax rules on its income. The parent should assess the likely tax position before choosing the subsidiary’s operating model, pricing policy and funding arrangements.
Where the parent and subsidiary transact with each other, transfer pricing rules may apply. Relevant transactions can include management fees, technical services, royalties, software licences, cost sharing, loans and guarantees. The pricing should comply with the applicable arm’s length requirements, and the group should maintain appropriate supporting documentation.
The tax analysis should also consider withholding tax on cross border payments, the availability of treaty benefits and the treatment of dividends distributed to the parent. Tax relief under a treaty depends on the relevant treaty provisions, residence, beneficial ownership and other applicable conditions.
A subsidiary should not simply book group charges without a clear contractual basis and evidence of the services or rights received. The company should establish an intercompany agreement framework and a process for reviewing related party transactions.
The parent should also consider indirect tax registration and invoicing obligations based on the subsidiary’s activities. The exact registrations depend on the goods or services supplied, locations and applicable thresholds.
7. Protect Intellectual Property, Confidential Information and Data
An Indian subsidiary may need access to the parent’s trademarks, software, technical information, business methods or confidential materials. The group should document the legal basis on which the subsidiary can use these assets.
The agreement should define the permitted use, territory, duration, fees and restrictions. It should also address ownership of improvements or new intellectual property created by employees and contractors in India. Without clear agreements, disputes can arise over who owns work product developed during the subsidiary’s operations.
The group should review employment contracts, consultancy agreements and confidentiality obligations to ensure intellectual property rights are properly assigned where appropriate. It should also check whether any local registrations or recordal steps are advisable.
Data protection is another important consideration. If the subsidiary collects customer information, manages employee records or accesses data held by the parent, the group should assess applicable Indian data protection and cybersecurity requirements. Cross border access and transfers should be reviewed in light of the data involved and the current legal framework.
8. Establish Employment and Operational Compliance
The subsidiary will need suitable employment contracts, policies and processes before hiring staff. These should address compensation, confidentiality, intellectual property, leave, termination and other employment terms relevant to the workforce.
The company must identify which labour laws and social security obligations apply to its establishment, employee numbers and activities. Requirements can differ according to the nature of the business and the state in which the subsidiary operates.
Depending on its activities, the company may also need registrations or licences relating to goods and services tax, professional tax, shops and establishments, import and export, environmental permissions or sector specific regulation.
The parent should avoid assuming incorporation alone authorises every planned business activity. Some approvals must be obtained before operations begin, and others may depend on the location, workforce or products involved.
9. Build a System for Ongoing Corporate Compliance
After incorporation, the subsidiary must maintain statutory records, hold required board and shareholder meetings, file annual returns and financial statements, and meet applicable accounting and audit obligations.
It should also monitor changes in shareholding, directors, registered office details and other corporate information, filing the prescribed forms within the applicable time limits. Where foreign investment is involved, relevant RBI reporting and annual foreign liabilities and assets reporting may also apply, depending on the circumstances.
The parent should establish a clear division of responsibility between its group finance team, Indian directors and local advisers. A compliance calendar helps ensure deadlines are not missed and records remain available for audits, banking reviews or future fundraising.
A well designed compliance process also makes it easier to distribute dividends, raise additional capital, restructure the group or sell the subsidiary in the future.
For businesses exploring foreign investment opportunities, the legal and operational model should be considered together. The subsidiary should be structured not only for initial entry but also for sustainable growth, governance and future changes in ownership.
Conclusion
Setting up an Indian subsidiary requires coordinated decisions on foreign investment eligibility, ownership, incorporation documents, funding, tax, intellectual property, employment and continuing compliance. Addressing these matters before launch helps the overseas parent avoid unnecessary delays and build a sound operating structure.
The most effective approach is to assess the planned business activities first, confirm the applicable approvals and then align the corporate structure, funding arrangements and compliance systems with those requirements. The final setup should be reviewed against the current law and the specific circumstances of the parent and its proposed Indian operations
Frequently Asked Questions
Can a foreign company own 100% of an Indian subsidiary?
Yes, a wholly owned subsidiary is permitted in many sectors, subject to the applicable FDI entry route, sectoral caps, approval requirements and other restrictions.
Does an Indian subsidiary need a resident director?
An Indian company generally must have at least one director who satisfies the statutory Indian residence requirement for the relevant financial year. The company should confirm the current requirements when appointing its board.
Is Government approval required to establish every Indian subsidiary?
No. Many sectors permit foreign investment under the automatic route. Prior approval may be required for specified activities, ownership structures or investors.
Can the overseas parent fund the subsidiary through a loan?
Potentially, but the loan must comply with the applicable borrowing and foreign exchange rules. The parent should not assume every intercompany loan is permitted.
What ongoing filings does an Indian subsidiary need to complete?
The company generally has annual corporate filings, financial statement and audit obligations, alongside tax and other activity specific compliance. Foreign investment may also trigger additional reporting.
Should the parent use an Indian subsidiary or a branch office?
The decision depends on the intended activities, regulatory permissions, tax position, liability structure and commercial objectives. A subsidiary is a separate Indian legal entity, while a branch office is an extension of the overseas company and has more restricted permitted activities.
Indian Business Acquisition
How Can a Foreign Company Acquire an Indian Business Through a Share Purchase or Business Transfer?
Indian Business Acquisition can be structured in two main ways: a foreign company can purchase shares in an existing Indian company or acquire its business through an asset purchase or transfer of an undertaking. Both structures can provide access to the Indian market, customers, employees, technology and established operations. However, they have different legal, regulatory, tax and commercial consequences.
The right structure depends on the business being acquired, the buyer’s investment eligibility, the liabilities involved and the parties’ commercial objectives. Before proceeding, a foreign buyer should assess India’s foreign direct investment rules, conduct legal and financial due diligence, examine tax implications and plan the transfer of contracts, employees and assets.
1. What Is the Difference Between a Share Purchase and a Business Transfer?
In a share purchase, the foreign buyer acquires shares in an existing Indian company. The company continues to own its assets, employ its staff and hold its contracts. The main change is in its ownership and, potentially, its management and control.
This structure can be useful where the buyer wants to acquire an established business with existing licences, customer relationships, intellectual property and operational systems. However, the buyer also acquires exposure to the company’s existing liabilities, including potential tax disputes, employment claims and regulatory non compliance.
A business transfer involves acquiring specified assets, operations or an undertaking from the seller. Depending on the structure, the buyer may acquire machinery, inventory, intellectual property, contracts, employees and other business assets without purchasing the shares of the company owning them.
A transfer may be structured as an itemised asset sale or as a transfer of an undertaking for a lump sum consideration. The legal and tax treatment depends on the transaction documents and the substance of the arrangement.
Neither structure is automatically better. A share purchase may preserve business continuity, while an asset acquisition may allow the buyer to select the assets and operations it wishes to acquire. The buyer must still assess which liabilities, contracts and regulatory obligations will follow the transaction.
2. Check Whether Foreign Investment Is Permitted in the Sector
Before negotiating an acquisition, the buyer should identify the Indian company’s business activities and determine the applicable foreign direct investment (FDI) conditions.
India permits foreign investment through the automatic route in eligible sectors, while other sectors require prior Government approval. Some activities are subject to sectoral caps, operating conditions or restrictions. Certain activities are prohibited for foreign investment.
The buyer should examine the relevant sectoral policy, the proposed ownership percentage and whether the acquisition would result in a change of control. A transaction involving a regulated business may require approval or notification to the relevant regulator, even where foreign investment is generally permitted.
The parties must also examine beneficial ownership. Restrictions concerning investors from countries sharing a land border with India can affect the acquisition, including certain changes in the beneficial ownership of an existing Indian investment. The applicable rules and any current exceptions should be checked against the buyer’s ownership structure.
The National Single Window System provides access to information about Government approvals and investment related processes. The buyer should use the relevant official guidance to identify approval requirements before committing to completion.
3. Conduct Legal Due Diligence Before Agreeing the Purchase
Legal due diligence helps the buyer understand what it is acquiring and identify risks that could affect the purchase price or transaction structure.
For a share purchase, the review should cover the company’s incorporation records, shareholding, constitutional documents, shareholder agreements, board approvals and existing charges over assets. The buyer should also examine material contracts, litigation, tax disputes, regulatory filings, intellectual property rights and compliance with applicable laws.
For a business transfer, due diligence should focus on the assets and operations being transferred. The buyer should verify ownership of the assets, identify any mortgages or security interests, check whether key contracts can be assigned and establish whether licences can be transferred or must be obtained afresh.
Employment matters also require attention. The parties should assess employee entitlements, accrued benefits, pending disputes and the process for transferring or offering employment to staff. The treatment of employees can differ according to the transfer structure and applicable employment laws.
The findings should inform the acquisition agreement. Material risks may justify specific warranties, indemnities, price adjustments, conditions precedent or an escrow arrangement. A buyer should not rely solely on the seller’s assurances without checking the underlying records.
4. Review Pricing, Valuation and Payment Requirements
A foreign company acquiring shares in an Indian company must consider the pricing rules applicable under India’s foreign investment framework.
The relevant requirements depend on the type of securities, whether the company is listed or unlisted, the residence status of the parties and the transaction structure. A valuation report may be required to support compliance with applicable pricing guidelines.
The buyer should also confirm the permitted payment route and ensure the transaction consideration is properly documented. Where consideration includes deferred payments, indemnity holdbacks, escrow arrangements or non cash elements, the parties should examine whether the proposed terms comply with applicable foreign exchange rules.
An asset or undertaking transfer requires a separate analysis. The parties should identify the assets being sold, the allocation of consideration and any applicable stamp duty or registration requirements. The tax treatment may depend on whether individual assets are transferred separately or an undertaking is transferred as a going concern under a qualifying structure.
Valuation is not merely a negotiation tool. It can affect regulatory compliance, tax calculations and the evidence required by banks or authorities.
5. Assess the Tax Consequences of Each Structure
Tax can materially affect the overall cost of an Indian business acquisition. The buyer and seller should model the likely tax consequences before deciding between a share purchase and a business transfer.
In a share purchase, the seller may incur tax on gains arising from the transfer of shares. The treatment depends on factors such as the nature of the shares, holding period, seller’s status, applicable exemptions and the tax law relevant to the transaction. The buyer should also consider withholding obligations where applicable.
In a business transfer, the tax outcome depends on the assets transferred and the legal structure used. A transfer of an undertaking for a lump sum may qualify for special treatment if it satisfies the statutory definition of a slump sale. An itemised asset sale may produce different results for different asset categories.
India’s Income Tax Act, 2025 came into effect on 1 April 2026. Transactions and tax periods must be analysed under the legislation applicable to the relevant period, including any transitional provisions. The Income Tax Department provides official tax legislation and guidance.
The parties should also consider indirect taxes, stamp duty, tax losses, carried forward credits and the availability of tax depreciation. The correct analysis depends on the precise transaction and should be completed before the purchase price is finalised.
6. Examine Contracts, Licences and Intellectual Property
An acquisition may be commercially attractive because of its existing contracts, licences, technology or customer relationships. However, these rights do not always transfer automatically.
In a share purchase, the company generally remains the same contracting entity. Even so, contracts may contain change of control clauses requiring consent or allowing termination when ownership changes. Regulatory licences may also impose conditions concerning ownership or management.
In a business transfer, the buyer must identify which contracts, permits and intellectual property rights can be assigned. Some contracts require the counterparty’s consent, while certain licences may be personal to the existing business and cannot simply be transferred.
Intellectual property due diligence should confirm ownership of trademarks, patents, software, designs, domain names and other material rights. The buyer should also examine employee and contractor agreements to confirm the business has the necessary rights to use and commercialise its technology.
The acquisition agreement should clearly identify which rights are included, which consents are required and who is responsible for obtaining them.
7. Prepare the Acquisition Agreement and Completion Conditions
The acquisition agreement should reflect the chosen structure and allocate the principal commercial and legal risks.
A share purchase agreement normally sets out the shares being sold, consideration, completion mechanics, warranties, indemnities and conditions precedent. It may also contain provisions concerning interim business conduct, restrictions on competing activities and post completion cooperation.
A business transfer agreement should identify the assets and liabilities included in the transaction, the consideration, the treatment of employees, contract assignments and the transfer of relevant records. The agreement should clearly distinguish assumed liabilities from those retained by the seller, subject to applicable law.
Conditions precedent may include regulatory approvals, third party consents, lender releases, satisfactory due diligence and corporate authorisations. The parties should agree what happens if a required approval is delayed or refused.
Where the acquisition involves an Indian company, the relevant corporate approvals and share transfer formalities must also be completed. Depending on the structure, additional filings, registrations or notifications may be required after completion.
8. Plan the Post Acquisition Integration
Legal completion is only one part of a successful acquisition. The buyer should prepare a plan for management transition, financial controls, employee communication, contract continuity and regulatory compliance.
For a share purchase, the buyer may need to appoint directors, update governance arrangements and implement new reporting systems. The company’s existing obligations remain in place, so outstanding filings and compliance issues should be addressed promptly.
For a business transfer, the buyer should confirm the assets have been delivered, relevant contracts have taken effect and any required registrations or licences are in place. The parties should also ensure employees, customers and suppliers understand the operational changes.
Sound business investment planning helps the buyer coordinate legal, financial and operational workstreams, rather than treating the acquisition as a single signing event.
A foreign company entering India for the first time should also consider whether it needs an Indian subsidiary, branch or another permitted business presence. The appropriate structure depends on its intended activities and the rules governing foreign entities in India. The decision to register a company is separate from the decision to acquire an existing Indian business, although both may form part of a broader market entry strategy.
Conclusion
A foreign company can acquire an Indian business through a share purchase or a business transfer, but the choice requires careful legal, regulatory, tax and commercial analysis. The buyer should confirm foreign investment eligibility, conduct due diligence, assess valuation and tax consequences, obtain necessary approvals and document the transaction properly.
Early planning helps identify risks before they affect the price or completion timetable. A structure designed around the buyer’s commercial objectives and India’s regulatory requirements provides a stronger foundation for a successful acquisition
Frequently Asked Questions
Can a foreign company directly acquire an Indian business?
Yes, subject to the applicable FDI rules, sectoral conditions, approvals and other legal requirements. The appropriate acquisition structure depends on the business and the buyer’s eligibility.
Is a share purchase better than a business transfer?
Neither is universally better. A share purchase preserves the existing company but exposes the buyer to its liabilities. A business transfer can allow the buyer to select assets and operations, but transferring contracts, licences and employees may require additional steps.
Does every foreign acquisition require Government approval?
No. Many investments fall under the automatic route. Approval may be required for specified sectors, investors or ownership structures. The applicable rules should be checked before completion.
What due diligence is required before acquiring an Indian company?
The review commonly covers corporate records, ownership, contracts, tax, litigation, licences, employees, intellectual property, assets, liabilities and regulatory compliance. The scope should reflect the transaction’s size, sector and risk profile.
What taxes apply to an Indian business acquisition?
The tax outcome depends on whether the transaction involves shares, individual assets or an undertaking, as well as the parties’ circumstances and applicable tax law. Tax advice should be obtained before agreeing the final structure and consideration.
Can the buyer choose which liabilities to acquire?
In an asset or business transfer, the parties can define the liabilities assumed under the agreement, subject to applicable law. In a share purchase, the company retains its liabilities because the company itself remains the same legal entity.
Investment Proceeds Repatriation
What Legal Checks Are Required Before Repatriating Sale Proceeds From an Indian Investment?
Investment Proceeds Repatriation refers to transferring money earned from an Indian investment, such as the sale of shares, outside India. For foreign investors, the process involves more than instructing a bank to send funds overseas. The investor must establish eligibility for repatriation, comply with applicable foreign exchange regulations, settle Indian tax liabilities and provide the required supporting documents.
India’s Foreign Exchange Management Act, 1999 (FEMA), the Foreign Exchange Management (Non Debt Instruments) Rules, 2019, and relevant Reserve Bank of India (RBI) directions form an important part of the legal framework. The precise requirements depend on the asset sold, the investor’s residential status, the original investment route and whether the investment was made on a repatriation basis. Completing these checks before requesting a transfer can help avoid banking delays, regulatory complications and unexpected tax costs.
1. Confirm Whether the Investment Is Eligible for Repatriation
The first step is to establish whether the investment was made on a repatriation basis. This determines whether the sale proceeds may be transferred abroad under the applicable foreign exchange rules. Foreign investors holding eligible Indian securities on a repatriation basis can generally remit the net sale proceeds overseas, subject to applicable conditions. These may include compliance with pricing requirements, payment of taxes and the submission of supporting documents to an authorised dealer bank.
The position may differ for investments made by Non Resident Indians (NRIs) or Overseas Citizens of India (OCIs) on a non repatriation basis. In such cases, the proceeds may need to be credited to an eligible Indian bank account, and any subsequent remittance must follow the rules applicable to the account and the source of funds. Investors should therefore review the original investment records, inward remittance evidence, bank statements and relevant declarations before initiating repatriation. The fact an investor is currently resident outside India does not, by itself, establish an unrestricted right to transfer every Indian asset’s sale proceeds abroad.
2. Check FEMA Compliance and the Applicable Investment Rules
FEMA regulates cross border payments and the movement of foreign exchange. The applicable requirements depend on the nature of the investment and the transaction through which the proceeds arose. For example, the sale of shares in an Indian company may be governed by the foreign investment consultants , including the Non Debt Instruments Rules and the RBI’s directions. A sale of immovable property, a withdrawal from an Indian bank account or the winding up of an Indian business may involve a different set of provisions. Before repatriation, the investor should confirm whether the original investment complied with the rules in force at the relevant time. Relevant checks may include the permitted investment route, sectoral limits, required approvals, pricing conditions and applicable reporting.
Historical non compliance should not be ignored. If an earlier filing was missed or the investment was not structured correctly, the investor may need to address the issue before the authorised dealer bank is satisfied with the proposed remittance. The RBI Master Direction on Foreign Investment in India provides an important starting point for eligible foreign investments in Indian companies. Investors should verify the latest version and any subsequent amendments before acting.
3. Verify the Sale Price and Valuation Requirements
Pricing compliance is another important consideration, particularly where the investment involves shares in an Indian company. FEMA pricing rules may apply to transfers of equity instruments involving residents and non residents. The relevant requirements depend on the investor categories, the type of instrument and the transaction structure. For unlisted shares, the parties may need appropriate valuation evidence to demonstrate compliance with the applicable rules. The sale agreement should clearly record the number and class of securities transferred, the consideration, the payment terms and the completion date. Supporting valuation documents should be retained where required.
Investors should not assume every sale price is acceptable simply because the buyer and seller have agreed to it. Nor should they assume the same valuation method applies to listed securities, unlisted shares and other investment assets. If the transaction falls outside the applicable pricing framework, further regulatory analysis may be necessary. Confirming the permitted price before completion can reduce the risk of delays when the seller later seeks to remit the proceeds.
4. Calculate and Settle Indian Tax Liabilities
Sale proceeds should not be treated as fully available for overseas transfer until the applicable Indian tax position has been assessed. The tax treatment depends on the asset, the acquisition and sale dates, the purchase cost, the nature of the gain, the seller’s status and any applicable tax treaty. Capital gains tax may arise when shares or other capital assets are sold. Other rules may apply to business assets, distributions or proceeds received during liquidation. The investor should obtain a transaction specific tax calculation and determine whether tax has been paid, withheld or otherwise accounted for. Where withholding tax applies, the parties should verify the amount and retain the relevant evidence. The buyer, Indian company or another responsible party may have obligations depending on the transaction.
Investors should also consider whether treaty relief is available and whether the documentation required to claim it has been provided. A treaty should not be assumed to eliminate Indian tax automatically. The authorised dealer bank may request tax payment evidence, a chartered accountant’s certificate, a tax undertaking or other documents appropriate to the remittance. The exact requirements can vary with the transaction and the bank’s compliance review.
5. Prepare the Documents Required by the Authorised Dealer Bank
Most repatriation requests are processed through an authorised dealer bank. The bank reviews the purpose of the remittance, the source of funds and the supporting records before allowing the transfer under the applicable rules. Depending on the investment, the documentation may include the original investment or subscription records, proof of inward remittance, the sale agreement, valuation reports, bank statements, tax documents and evidence of any required regulatory approvals. Where the proceeds arise from shares in an Indian company, the bank may also seek corporate records, details of the original acquisition, evidence of the share transfer and confirmation of relevant reporting. The documents required for a listed investment may differ from those needed for a private company transaction.
The investor should ask the bank for a transaction specific document list before submitting the remittance request. This is particularly useful where the investment was made several years earlier, records are held across multiple institutions or the seller has changed residential status. Clear and consistent records can help the bank trace the investment from the original funding through to the sale and proposed remittance.
6. Confirm Reporting and Transfer Formalities
Regulatory reporting is separate from the commercial completion of a transaction. Depending on the nature of the investment, the parties may have needed to file prescribed forms or meet other reporting requirements when the investment was made or transferred. For foreign investment in Indian companies, reporting obligations can include filings associated with the issue or transfer of equity instruments. The applicable form and responsible party depend on the transaction. Not every sale requires the same filing, and an investor should not assume a particular form applies to all transfers.
Where a filing was required, the parties should confirm whether it was submitted correctly and retain the acknowledgement. If an error or delay is identified, they should assess the appropriate correction or regularisation process before proceeding. The RBI regulations on payment and reporting of non debt instruments set out relevant requirements for specified foreign investment transactions. The current rules should be checked against the facts of the proposed remittance.
7. Check the Correct Bank Account and Permitted Remittance Route
Even where repatriation is legally permitted, the proceeds must be routed through an appropriate banking channel. The correct route may depend on whether the seller is a foreign company, an individual non resident, an NRI or an OCI, and whether the investment was held on a repatriation or non repatriation basis. Relevant account rules may determine whether proceeds can be remitted directly overseas or must first be credited to an eligible Indian account. Investors should confirm the beneficiary account details, currency, permitted payment method and any conversion or banking charges. They should also ensure the amount requested matches the net proceeds available after applicable deductions.
Where the proceeds are held in an NRO account or arise from an asset subject to separate remittance limits, the investor should verify the applicable remittance facility rather than relying on the rules for foreign investment in shares. For investors planning future NRI investment opportunities, it is sensible to consider repatriation conditions when selecting the investment route. The ability to transfer money out of India may depend partly on how the investment was funded and documented at the beginning.
8. Identify Issues That Could Delay Repatriation
A remittance may be delayed where the bank cannot reconcile the original investment with the sale proceeds, tax evidence is incomplete or the investor’s regulatory status is unclear. Inconsistent names, missing transaction records, valuation concerns and outstanding reporting requirements can also create difficulties. Another common issue is assuming the sale agreement alone proves the proceeds can be remitted. The agreement records the commercial arrangement, but it does not replace FEMA compliance, tax obligations or the bank’s documentation requirements.
Where an Indian business is being sold or wound up, the investor should also establish whether the proceeds represent share sale consideration, a dividend, a liquidation distribution, a loan repayment or another category of payment. Each may have different legal and tax consequences. Investors dealing with a new Indian venture should distinguish between company formation online and the later process of transferring investment proceeds overseas. Incorporation is only one stage of a company’s life cycle. Proper investment records, regulatory filings and tax documentation remain important when funds are eventually repatriated.
Conclusion
Investment proceeds repatriation from India requires a coordinated review of foreign exchange compliance, tax liabilities, pricing rules, reporting and banking documentation. The investor should first confirm the basis on which the investment was held, then establish the legal route for remitting the net proceeds and assemble the evidence required by the authorised dealer bank. A transaction specific review before the remittance request can help identify problems early and reduce avoidable delays. As the applicable rules depend on the asset and investor category, the final checklist should be confirmed against the latest regulations and the facts of the investment.
Frequently Asked Questions
Can a foreign investor freely transfer sale proceeds from India overseas?
Not in every case. Repatriation is generally possible where the investment and proposed remittance satisfy the applicable FEMA rules, tax requirements and supporting documentation conditions.
Is RBI approval required for every investment proceeds repatriation?
No. Many eligible transactions can be processed by an authorised dealer bank under general permissions. Specific approval may be needed where the transaction falls outside the permitted framework or a particular rule requires it.
Must Indian tax be paid before sale proceeds are remitted?
Applicable Indian taxes must be properly accounted for. Depending on the transaction, this may involve payment of tax, withholding, certificates or other supporting evidence.
Can proceeds from shares held on a non repatriation basis be transferred abroad?
The treatment depends on the investor category, the original investment conditions and the relevant account and remittance rules. The proceeds should not be assumed to be freely repatriable merely because the seller is now outside India.
What documents will a bank request before allowing repatriation?
The bank may request proof of the original investment, sale documents, bank statements, tax evidence, valuation records, relevant regulatory filings and any required approvals. The precise list depends on the transaction.
What happens if earlier FEMA reporting was missed?
The issue should be identified and assessed before the remittance request proceeds. The appropriate corrective or regularisation steps depend on the nature of the omission and the applicable rules.
Shareholder Exit Rights
How Can Foreign Investors Structure Put Options, Call Options and Exit Rights in Indian Shareholder Agreements?
Shareholder Exit Rights are an important consideration for foreign investors entering an Indian company. A carefully drafted shareholders’ agreement can establish when an investor may sell its shares, how an exit price is determined and what happens if the founders or other shareholders cannot agree on a sale. Put options, call options, drag along rights and tag along rights can help allocate these risks before a dispute arises.
However, an exit clause is not effective merely because the parties have signed it. Foreign investors must consider the Foreign Exchange Management Act, 1999 (FEMA), applicable pricing rules, company law and the company’s constitutional documents. The objective is to create commercially workable exit mechanisms while ensuring the proposed transfer can be implemented lawfully.
Why Do Foreign Investors Need Contractual Exit Rights?
Foreign investors may commit capital for several years without having a readily available market in which to sell their shares. This is particularly relevant when investing in an unlisted Indian private company. The investor may depend on a future acquisition, a sale to another investor, a promoter purchase or a public listing to realise its investment.
Exit rights help the parties agree in advance on possible routes out of the investment. They can also clarify what happens if the business underperforms, the founders breach agreed obligations, a planned sale does not occur or the shareholders reach a deadlock.
A strong exit framework should address both the investor’s commercial objectives and the company’s practical ability to honour the arrangement. An agreement promising an exit at a fixed return may create regulatory concerns even if the parties consider it commercially reasonable. The terms must therefore be reviewed alongside the rules governing foreign investment and share transfers.
1. Understand How a Put Option Works
A put option gives an investor the contractual right to require another party to purchase its shares when specified conditions are met. For example, a foreign investor may negotiate a put option exercisable if the company fails to meet an agreed milestone, a defined period expires or a material contractual breach remains unresolved.
The clause should identify the party required to buy the shares, the triggering event, the exercise period and the process for serving an exercise notice. It should also explain how the number of shares to be transferred and the price will be determined.
The identity of the proposed purchaser matters. A put option against the Indian company itself raises different company law considerations from an option requiring the founders or another shareholder to buy the investor’s shares. A company purchase must comply with the applicable rules on buybacks, capital reduction or other permitted mechanisms. A founder purchase must be assessed against the founder’s contractual obligations and ability to complete the transaction.
For a non resident investor, the exit price must also comply with the applicable FEMA pricing framework. A contractual right to sell does not automatically permit the investor to receive a guaranteed return. The clause should be drafted with regulatory conditions in mind, rather than relying on a fixed price or internal rate of return without further analysis.
2. Structure Call Options Carefully
A call option gives the holder the right to require another party to sell shares on agreed terms. In an Indian joint venture, for example, a foreign investor may seek a call option over a local partner’s shares if the partner commits a serious breach or a deadlock prevents the business from operating effectively.
The agreement should define the circumstances in which the call option becomes exercisable. Triggers may include a material breach, an agreed deadlock process, a change of control or another clearly defined event. Vague triggers can create uncertainty and increase the risk of litigation.
The clause should also specify the notice process, completion timetable, payment arrangements and transfer documents. Where the option concerns shares held by a non resident or involves a transfer between a resident and a non resident, the parties must examine the applicable pricing and transfer requirements.
Call options should not be treated as a substitute for a proper governance framework. Reserved matters, board representation, information rights and deadlock resolution procedures can help prevent disagreements from escalating to an exit. The option should function as part of the wider contractual structure.
3. Address FEMA Pricing and the Risk of an Assured Return
FEMA compliance is central to exit planning for foreign investors. The relevant framework includes the Foreign Exchange Management (Non Debt Instruments) Rules, 2019, and the applicable Reserve Bank of India directions. The precise requirements depend on the transaction, the parties’ residency status, the type of security and the route through which the investment was made.
Indian foreign investment rules permit optionality clauses in relevant circumstances, subject to applicable conditions. However, an investor’s exit cannot simply be structured to guarantee a predetermined return regardless of the value of the shares or the rules applying at the time of transfer.
For an unlisted company, the pricing framework generally requires the relevant transfer to meet the applicable fair value and pricing conditions. The precise methodology, certification and permitted price depend on the transaction and the current rules. Listed securities may be subject to a different pricing framework.
Consider a foreign investor seeking an option to sell its shares to a resident founder after five years. The agreement should not assume the founder can automatically purchase the shares at the original investment amount plus a fixed annual return. Instead, the clause should provide for a legally compliant pricing mechanism and completion process, with appropriate qualifications for regulatory requirements.
The parties should obtain transaction specific advice before agreeing to an exit formula. A provision that appears commercially attractive may prove difficult to implement if it conflicts with mandatory foreign exchange rules.
4. Use Tag Along Rights to Protect Minority Investors
A tag along right allows a minority shareholder to participate in a sale by another shareholder, usually when a founder or controlling investor proposes to sell shares to a third party. It helps prevent the minority investor from being left in a company under new ownership without an opportunity to exit on the agreed terms.
The clause should specify the transactions which trigger the right, the minimum percentage of shares being sold and the notice the selling shareholder must provide. It should also explain whether the minority investor may sell all its shares or only a proportionate amount.
The agreement should set out how the proposed purchaser will be notified and how the sale will proceed if the purchaser is unwilling to acquire the tagged shares. The parties should also consider what happens if the buyer changes the proposed terms before completion.
For foreign investors, tag along rights must operate consistently with the applicable transfer restrictions, pricing rules and required documentation. Clear drafting can reduce uncertainty when a control sale takes place.
5. Consider Drag Along Rights for a Complete Company Sale
Drag along rights allow specified shareholders to require other shareholders to participate in a sale, subject to the conditions in the agreement. They can help a buyer acquire the entire company rather than negotiate separately with numerous minority shareholders.
A foreign investor may seek a drag along right to facilitate an eventual sale of the business. Founders and minority investors, however, may want safeguards against being forced to sell at an unfair price or on materially different terms.
The agreement should define the minimum approval threshold, the type of transaction covered and the protections available to shareholders being dragged into the sale. These may include equal treatment on price per share for the same class, limits on representations and warranties, and a requirement for the buyer to provide the agreed consideration.
The parties should also distinguish between the contractual right to require participation in a sale and the legal steps needed to transfer the shares. Corporate approvals, transfer documentation, applicable pricing rules and regulatory reporting may still be required.
6. Define Deadlock, Default and Long Stop Exit Mechanisms
Not every exit should depend on a planned sale. A joint venture may become unworkable when the shareholders cannot agree on a budget, business plan or major strategic decision. The agreement should establish a clear deadlock process before either party seeks to force an exit.
A typical process may require escalation to senior representatives, followed by a defined negotiation period and, where appropriate, mediation. If the deadlock continues, the parties may use a contractual sale process, call option, put option or another mechanism, provided the structure is legally permissible.
Default provisions should distinguish between serious breaches and minor failures. The agreement may provide for notice and a cure period before an exit right becomes exercisable. This reduces the risk of a disproportionate response to a remediable breach.
A long stop date can also be useful when an exit depends on an event such as a public listing or acquisition. The agreement should specify what happens if the event has not occurred by the agreed date. The outcome should not be left to informal negotiations after the parties have already invested substantial time and capital.
7. Align the Shareholders’ Agreement with Company Documents
An exit right may be difficult to implement if the shareholders’ agreement conflicts with the company’s articles of association or other governing documents. The parties should review transfer restrictions, pre emption rights, consent requirements and provisions governing the registration of share transfers.
Under the Companies Act, 2013, the treatment of transfers differs in certain respects between private and public companies. The contractual rights of shareholders and the company’s obligations must be assessed in the context of the relevant provisions and constitutional documents.
The agreement should also address the cooperation required from the company and its shareholders when an exit is exercised. This may include signing transfer instruments, providing corporate approvals, updating statutory records and completing applicable filings.
During startup investment planning, founders and investors should agree on exit principles alongside valuation, governance and funding terms. Integrating the provisions early is generally easier than reconciling inconsistent documents during a future sale.
8. Draft for Enforceability and Practical Completion
An exit clause should be precise enough to operate when the parties disagree. It should identify the relevant parties, triggering conditions, exercise period, pricing mechanism, payment process and consequences of non cooperation. It should also explain how disputes about valuation or the satisfaction of a trigger will be resolved.
The parties should consider whether the agreement needs an independent valuation process, expert determination, arbitration or another dispute resolution mechanism. These provisions should complement, rather than contradict, the main exit clauses.
Foreign investors should also review the practical consequences of a transfer, including tax treatment, remittance requirements, applicable approvals and reporting obligations. Where an option involves a cross border transfer, the company should coordinate the contractual process with its authorised dealer bank and advisers as appropriate.
A foreign investor intending to register a company name or establish a new Indian entity should consider exit rights as part of the wider investment structure, particularly where local partners or future co investors will hold shares. The right structure at the outset can reduce uncertainty when ownership changes later.
Conclusion
Put options, call options, tag along rights and drag along rights can give foreign investors and Indian founders greater certainty about how an investment may end. Their effectiveness depends on clear triggers, workable pricing provisions, aligned corporate documents and compliance with FEMA and company law.
The best exit structure is one which balances commercial protection with legal enforceability. Investors and companies should review the proposed rights before signing, test how they would work in realistic scenarios and obtain advice tailored to the transaction and the rules in force at the time of exercise
Frequently Asked Questions
Are put options permitted in Indian shareholders’ agreements?
Put options may be included in shareholders’ agreements, subject to the applicable legal and regulatory framework. Where a non resident investor is involved, the option’s exercise and pricing must comply with the relevant FEMA requirements. The specific arrangement should be reviewed before signing.
Can a foreign investor receive a guaranteed return through a put option?
A foreign investor should not assume a contractual promise of a fixed return will be permissible. The exit must comply with applicable pricing and foreign exchange rules. The clause should provide a legally compliant method of determining the exit price.
What is the difference between a put option and a call option?
A put option allows its holder to require another party to purchase specified shares. A call option allows its holder to require another party to sell specified shares. Both depend on the contractual terms and applicable law.
Are tag along and drag along rights enforceable in India?
These rights can form part of enforceable contractual arrangements, subject to the agreement, applicable company law and other legal requirements. Their practical implementation depends on clear drafting, appropriate corporate documents and compliance with relevant transfer rules.
Should exit rights be included in the articles of association?
The shareholders’ agreement and articles of association should be reviewed together. Depending on the structure, relevant provisions may need to be reflected in the articles to support corporate implementation. The appropriate drafting depends on the company and transaction.
MHCO Updates
Supreme Court
SUPREME COURT HOLDS YES BANK ADMINISTRATOR LACKED AUTHORITY TO WRITE OFF RS. 8,415 CRORE AT-1 BONDS
In Yes Bank Limited & Anr. v. Axis Trustee Services Limited & Ors. (Civil Appeal No. 3182 of 2025 and connected matters, judgment dated 15 October 2026), the Supreme Court dismissed the appeals and upheld the Bombay High Court’s decision setting aside the write-down of Yes Bank’s Basel III-compliant Additional Tier 1 (“AT-1”) Bonds. The Court held that the Administrator could not write down the bonds contrary to the final Reconstruction Scheme or exercise a regulatory power vested in the Reserve Bank of India (“RBI”).
BACKGROUND
Yes Bank issued AT-1 Bonds worth Rs. 3,000 crores in December 2016 and Rs. 5,415 crore in October 2017. Following a steep deterioration in Yes Bank’s financial position, the Central Government imposed a moratorium on 5 March 2020, and the RBI appointed an Administrator. A draft reconstruction scheme published on 6 March 2020 expressly provided for the AT-1 Bonds to be permanently written down in full. However, the final Yes Bank Limited Reconstruction Scheme, notified on 13 March 2020, omitted that clause. On 14 March 2020, the Administrator nevertheless ordered a full write-down of the Rs. 8,415 crore AT-1 Bonds. Therefore, the trustee and bondholders challenged the action, and the Bombay High Court set it aside.
CONTENTIONS OF THE PARTIES
The appellants, including Yes Bank, the RBI and the Union of India, contended that the Administrator was empowered under Section 36ACA of the Banking Regulation Act, 1949 (“Banking Regulation Act”), the RBI’s Master Circular on Basel III Capital Regulations and the Information Memorandum to write down the bonds. They argued that invocation of Section 45 of the Banking Regulation Act triggered the point of non-viability and that the write-down, followed by SBI’s infusion of capital, was necessary to revive Yes Bank. They also argued that the reconstruction process continued after notification of the Scheme.
The respondents contended that the final Reconstruction Scheme deliberately omitted the draft provision for writing down the bonds. They argued that the Administrator could not write down the bonds after the Scheme came into force and that, under the Master Circular, the relevant action had to be taken before reconstruction. They further submitted that the power to determine the write-down at the point of non-viability belonged to the RBI, not the Administrator.
COURT’S FINDINGS
The Court held that the omission of the write-down clause from the final Reconstruction Scheme reflected a conscious decision not to deal with the bonds through the Scheme. The Administrator could not reverse that decision. A general clause preserving existing instruments did not confer a specific power to write down the bonds; the action was therefore ultra vires the Master Circular read with the Reconstruction Scheme.
The Court further held that the phrase “before reconstitution” in the Master Circular meant before the Reconstruction Scheme came into force, and not at any time while the Scheme’s effects continued. Once the point of non-viability was triggered, the RBI was required to determine the treatment of the bonds. The Administrator, whose statutory role was to act as a substitute for the Board of Directors, could not assume the RBI’s regulatory power. The Court observed that financial necessity could not excuse non-compliance with the prescribed procedure. It accordingly dismissed the appeals and clarified that its observations would not influence other pending proceedings.
MHCO COMMENT
The judgment reinforces that regulatory and administrative powers must be exercised strictly within the limits prescribed by statute and the applicable regulatory framework. The commercial necessity of rescuing a bank cannot override the authority, timing and procedure mandated by law.
The decision is also significant for the distinction it draws between the Administrator’s powers as a substitute for the Board of Directors and the RBI’s independent regulatory powers. The Administrator cannot assume a function specifically entrusted to the RBI. Further, a general provision preserving existing contracts cannot be used to imply a specific power that the final Reconstruction Scheme has omitted.
For market participants and financial institutions, the judgment highlights the importance of consistency between a reconstruction scheme, the RBI’s capital regulations and the terms of the relevant bond documentation. It also draws attention to investor-protection concerns surrounding the sale of complex, high-risk capital instruments to retail investors.
Date: 19 October 2026
By:
Mr. Bhushan Shah, Partner
Ms. Sayali Kshirsagar, Associate
Mr. Abhishek Nair, Associate
Disclaimer: This legal update is intended for general information purposes only and does not constitute legal advice. Readers are advised to seek specific legal advice before acting upon any information contained herein.
Litigation
LITIGATION UPDATE | SUPREME COURT UPHOLDS OCCUPANTS' RIGHTS IN REDEVELOPMENT PROJECTS, REINSTATES MHADA ORDERS FOR PERMANENT ALTERNATE ACCOMMODATION
Overview:
The Supreme Court of India, vide its judgment dated July 23, 2026, in Mahabanoo Contractor and Another v. Kalikund Developers and Others (Civil Appeal No. 9342 of 2026), set aside a Bombay High Court decision and ruled in favour of the occupants of a redeveloped cessed building. The Supreme Court upheld the Maharashtra Housing and Area Development Authority’s (MHADA) orders directing the developer to execute the Permanent Alternate Accommodation Agreement (PAAA) and hand over possession. The ruling firmly establishes that a PAAA executed under the Maharashtra Housing and Area Development Act, 1976 (MHAD Act) and the Development Control (DC) Regulations is not merely a private arrangement but is governed by a statutory scheme protecting occupants' rights.
Brief Background and Facts:
The dispute arose regarding a cessed building unfit for human habitation, which the developer (Respondent No. 1) undertook to demolish and redevelop under the MHAD Act, obtaining a No Objection Certificate (NOC) from MHADA. Occupants vacated the premises on the assurance of alternate accommodation in the reconstructed building.
The first Appellant and the late Ms. Gool Peshotan Unwalla were joint occupants of Room No. 5 on the third floor of the old building. Following the redevelopment, the developer refused to honour the PAAA executed on 17 October 2019, which granted the Appellants three flats (inclusive of fungible area) totalling 309.98 sq. mtrs. Instead, the developer offered a smaller area, contending that the fungible Floor Space Index (FSI) was not fully utilized due to a reduction in the building's height from 34 to 30 floors.
Upon the Appellants' complaint, MHADA issued orders on 28 May 2025, and 27 June 2025, directing the developer to register the PAAA and hand over possession, which were followed by a Show Cause Notice on 10 July 2025 when the developer failed to comply with the orders. The developer challenged the orders and the Show Cause Notice in the Bombay High Court, which stayed MHADA's actions by classifying the PAAA as a "private arrangement" amenable only to civil court jurisdiction. The Hon’ble High Court recorded the developer's undertaking to keep two flats encumbrance-free until a civil suit was decided. Subsequently, the developer filed a civil suit challenging the validity of the PAAA in its entirety.
Contentions of the Parties:
The Appellants (Occupants): The Appellants emphasized the statutory definition of 'occupant' under the MHAD Act and Rule 33(7) of the DC Regulations. They argued that the PAAA was a statutory requirement enforced by MHADA, not a private arrangement. They further relied on contemporaneous public notices, the certified list of tenants by MHADA, and the developer's NOC, all of which documented the first Appellant as a rightful joint occupant.
The Respondents (Developer): The Respondents contended that the PAAA was a concocted document executed by a former expelled partner without proper authorization. They argued that upon the original tenant's death, the tenancy was extinguished, leaving the Appellants without rights to the premises. Furthermore, they asserted the carpet area allotted in the PAAA was excessive compared to the original tenement's area, especially considering that the FSI was not fully utilised.
Court’s Findings:
The Division Bench of the Supreme Court consisting of the Hon’ble Justice Shri J.B. Pardiwala and the Hon’ble Justice K. Vinod Chandran made several key observations:
Statutory Nature of the PAAA: The Hon’ble Supreme Court held that the High Court had misconstrued the PAAA as a mere private arrangement. It was held that the PAAA was executed under the MHAD Act, which is a statutory scheme, and was meant to facilitate redevelopment while ensuring that the original occupants were not displaced. Its enforcement therefore fell squarely within MHADA's regulatory purview.
Definition of 'Occupant': The Hon’ble Court held that the MHAD Act defines "occupier" under Section 2(25) as encompassing more than just the statutory tenants. It was held that the first Appellant’s status as an occupant was firmly established by multiple contemporaneous documents, including the developer's own 2010 public notice and MHADA's certified list.
Developer's Conduct and Internal Disputes: The Hon’ble Court rejected the developer's attempt to use internal partnership disputes to invalidate agreements made with the occupants, stating that the occupants were not even made a party to the consent terms executed between the partners. It was held that the settlement of inter-se disputes between partners cannot absolve the developer from obligations under a validly executed PAAA, on the basis of which vacant possession was originally obtained. Additionally, it was held that the developer's failure to utilize the full fungible area does not justify resiling from the agreed allotments.
Mala Fide Civil Suit: The Hon’ble Court found the civil suit filed by the developer to be misconceived and mala fide in nature because it sought to challenge the Appellants' very claim as occupants contrary to the undertaking given by the developer to the High Court.
Judgment:
The Supreme Court allowed the appeal, setting aside the Bombay High Court's judgment and reviving MHADA’s original orders. The Hon’ble Court directed the developers to execute the PAAA and hand over possession of the three apartments within two months and stated that if they failed to do so, the Appellants were entitled to recover damages calculated at the monthly rental value of the flats. The Hon’ble Court further restrained the High Court from proceeding with the developer's civil suit and imposed heavy costs on the developer.
MHCO Comment:
This pivotal judgment strictly curtails the dilatory tactics often employed by developers in redevelopment schemes to avoid handing over agreed-upon permanent alternate accommodations. By reiterating that the PAAA is a statutory instrument governed by the MHAD Act, rather than a standard private contract, the Supreme Court has fortified the regulatory authority of bodies like MHADA to intervene and enforce these agreements. For real estate practitioners and developers, this ruling serves as a stern reminder that internal management disputes or changes in project specifications cannot be utilized to prejudice the vested statutory rights of certified occupants.
By:
Mr. Akash Jain, Associate Partner
Mr. Divyang Salvi, Associate
Ms. Diva Lathi, Associate
SEBI Update
REGULATORY UPDATE | SEBI ORDERS VARANIUM CLOUD TO RESTORE & DISGORGE FUNDS OVER IPO & RIGHT ISSUE FRAUD
The Securities and Exchange Board of India (“SEBI”) on 25 August 2025 passed a Final Order against Varanium Cloud Limited (“VCL”) and its key management for alleged fraudulent and misleading activities in connection with its Initial Public Offer (IPO), Rights Issue and subsequent disclosures.
BACKGROUND
The proceedings stemmed from SEBI’s preliminary examination pursuant to media reports and complaints regarding VCL’s financial statements and corporate announcements, which led to an Interim Order dated 10 May 2024 against VCL and its MD/Chairman, Harshwardhan Hanmant Sabale (Mr Sabale).
VCL raised approximately Rs 40.39 crore through its IPO in September 2022 (primarily for Edge Data Centres and Edmission Digital Learning Centres) and proposed a further Rs. 48.45 crore through a Rights Issue in September 2023. SEBI examined the utilisation of issue proceeds, financial statements, Prospectus disclosures, corporate announcements, related-party transactions, and the role of directors, the CFO, the merchant banker and other intermediaries.
SEBI’S FINDINGS
SEBI found that VCL misrepresented its financial statements and prospectus by showing fictitious sales and purchases, and that its disclosures on utilisation of IPO proceeds (including the Statement of Deviation dated 17 November 2023) were incorrect and misleading.
SEBI found that IPO and Rights Issue proceeds of Rs. 62.51 crore were diverted to related parties and other entities, including Rs. 32.73 crore transferred directly to Mr Sabale’s personal account. BM Traders (operated by Mr Raj Jagtani) received Rs. 19.66 crore in aggregate from the issue proceeds, of which Rs. 15.60 crore was transferred onwards; and that no adequate evidence of genuine business purpose was produced.
SEBI found several business announcements by VCL to be false and unsubstantiated. SEBI also found that the Company also failed to support the substantial increase in reported revenues (including those of its US subsidiary) with invoices, contracts or employee details. Pending litigation was omitted from the Letter of Offer, and the Prospectus contained material omissions and misstatements. Liability was fastened on the Company, its MD, Executive Directors and CFO.
SEBI found that the lead manager, First Overseas Capital Limited (FOCL), failed to exercise independent due diligence and did not disclose pending litigation. SEBI rejected FOCL’s defence that it could rely on the Company’s representations and third-party reports. Athos Capital Advisors Private Limited (ACAPL) and Mr Jinesh Mehta were held to have aided and abetted the misrepresentations; ACAPL received approximately Rs. 2.50 crore from VCL, and Mr Mehta admitted drafting portions of the Prospectus and assisting with fundraising.
SEBI’S DIRECTIONS
VCL was directed to bring back Rs. 62.51 crore (with 12% p.a. interest) within three months. Mr Sabale was directed to disgorge unlawful gains of Rs. 128.77 crore (with 12% p.a. simple interest) to the Investor Protection and Education Fund. VCL and Mr Sabale were debarred from the securities market for 7 years.
ACAPL and Mr Jinesh Mehta were debarred for 2 years; Mr Raj Jagtani/BM Traders for 4 years; the Executive Directors and CFO (Mr Vinayak Jadhav, Mr Mukundan Raghavan and Mr Fahim Shaikh) for 1 year; and FOCL for 2 years (to run consecutively with an earlier debarment). Monetary penalties were also imposed, including Rs. 20.40 crore on Mr Sabale, Rs. 13 crore on VCL and Rs. 10.10 crore on Mr Raj Jagtani.
Proceedings against the Company Secretary (Ms Hetal Somani) and a Non-Executive Director (Mr Kalpesh Acharekar) were disposed of without directions or penalty, the allegations against them being found unsustainable.
MHCO COMMENT
The order is significant for its treatment of misrepresentation in financial statements and public-issue disclosures, diversion of IPO and Rights Issue proceeds, and the accountability of directors, KMPs and intermediaries. It reiterates that a lead manager must conduct independent due diligence and cannot merely rely on the issuer’s representations or third-party reports.
SEBI did not fasten liability on every director or officer; allegations against the Company Secretary and non-executive director were dropped for want of material. Overall, SEBI characterised the matter as a fraudulent scheme of raising public funds on misleading disclosures, followed by diversion of proceeds and creation of a false picture of the Company’s performance. The restoration, disgorgement, debarment and penalty directions reflect the seriousness with which the conduct was viewed.
By:
Mr. Bhushan Shah, Partner
Mr. Abhishek Nair, Associate
Ms. Sayali Kshirsagar, Associate
Rea Estate
BOMBAY HIGH COURT ALLOWS REFUND OF STAMP DUTY PAID ON CANCELLED DEVELOPMENT AGREEMENT
The Bombay High Court, vide judgment dated 20 August 2026 in Sai Innovation v. Joint District Registrar and Collector of Stamps, Pune City & Ors. (Writ Petition No. 7566 of 2016), has held that a Development Agreement which fails to achieve its intended purpose and is subsequently cancelled can qualify for refund of stamp duty under Section 47(c)(5) of the Maharashtra Stamp Act, 1958 (“the Stamp Act”), and that such an agreement can avail the extended limitation period under the proviso to Section 48(1) where stamp duty has been calculated with reference to Article 25 of Schedule I.
Background:
Sai Innovation had entered into a Development Agreement (“said Agreement”) dated 15 April 2013 with the owners of land at Village Mauje Balewadi, Pune, for development of approximately 8,000 sq. metres of land and paid stamp duty under Article 25 read with Article 5 of Schedule I to the Stamp Act. The owners were unable to obtain sanction of the building plans within a reasonable time, and disputes subsequently arose between the parties. The said Agreement was therefore cancelled by a registered Deed of Cancellation (“said Deed”) dated 18 February 2014, registered on 24 February 2014, and the consideration received was returned. Sai Innovation thereafter applied on 7 April 2014 for refund of the stamp duty. The Respondent Nos 1&2 vide their orders dated 11 August 2014 and 6 December 2014 (“Impugned Orders”) respectively, rejected the refund application of the Petitioner, principally on the ground that the said Agreement was not a “conveyance” and therefore did not fall within the proviso to Section 48(1) of the Stamp Act.
Issue:
The Court dealt with the following issues:
Whether the said Agreement had failed to achieve its intended purpose to attract Section 47(c)(5) of the Stamp Act;
Whether a Development Agreement could avail the benefit of the proviso to Section 48(1), particularly where stamp duty was calculated as per Article 25 of Schedule I;
Whether the reference to “actual, open possession” in Clause 13 of said Agreement be interpreted as transfer of possession to the developer, notwithstanding Clause 11 of the said Agreement which described the developer as a licensee; and
Whether the Respondents could subsequently rely upon the alleged transfer of possession as a ground for rejecting the refund claim, when the refund claim had initially been rejected by the Impugned Orders on other grounds, and the issue of possession did not form part of the reasons recorded in those orders.
Key Findings
The Court, while differentiating between Section 47 and Section 48 of the Stamp Act, held that while Section 47 is the main provision that gives the right to a refund of stamp duty, Section 48 only deals with the time limit. In the present case, the proposed development under the said Agreement was never acted upon, and the parties later cancelled the said Agreement by the said Deed. As a result, the transaction had clearly failed to achieve its intended purpose under Section 47(c)(5) of the Stamp Act. The Court therefore said the refund claim had to be examined first under Section 47 and could not be turned down simply by pointing to the limitation period.
On the question of possession, the Court held that Clause 13 of the said Agreement could not be read in isolation from Clause 11. Although Clause 13 referred to “actual, open possession”, Clause 11 expressly described the developer’s rights as those of “a licensee for development”. Reading the Agreement as a whole, the Court concluded that the developer was granted only a limited contractual licence to enter the property and undertake development activities, and that there was no transfer of legal or exclusive possession. The Court also noted that the absence of a separate possession receipt, by itself, did not establish that possession had been transferred.
Held
In light of the above reasoning, the Court allowed the writ petition and quashed the Impugned Orders passed by the Respondents. The Court held that the refund application was filed within the extended period prescribed under the proviso to Section 48(1) of the Stamp Act and, accordingly, rejected the Respondents’ objection that the claim was barred by the ordinary six-month limitation period.
MHCO Comment
Parties seeking refund of stamp duty on a cancelled Development Agreement should note that Section 47 governs the substantive entitlement to refund, while the proviso to Section 48(1) determines the applicable limitation period. Further, the legal character of a Development Agreement should be assessed by reading the same meaningfully and not in isolation from other clauses provided therein.
By:
Mr. Bhushan Shah, Partner
Ms. Meeta Kadhi, Associate Partner
Mr. Saptadip Nandi Chowdhury, Associate
LIFE AT MHCO


PRACTICE AREA
Private Limited Company Registration in India
Setting up a Company in India
Foreign Direct Investment (FDI) in India
Foreign Business Registration in India
Small Business Registration in India
GET IN TOUCH
Mumbai: Surya Mahal, 2nd Floor 5, Burjorji Bharcha Marg Fort, Mumbai-400 023 India
Contact No.: T: +91-22-40565252
E: contact@mhcolaw.com
Delhi: C-9, Lower Ground Floor Jangpura Extension, New Delhi-110 0014 India
Contact No.: T: +91-11-40196496
E: contact@mhcolaw.com
Contact No.: T: +91-22-40565252
E: contact@mhcolaw.com
Delhi: C-9, Lower Ground Floor Jangpura Extension, New Delhi-110 0014 India
Contact No.: T: +91-11-40196496
E: contact@mhcolaw.com
2025 - MANSUKHLAL HIRALAL & CO.
Need Help? Chat with us